Storm damage claims
Storm damage insurance claims
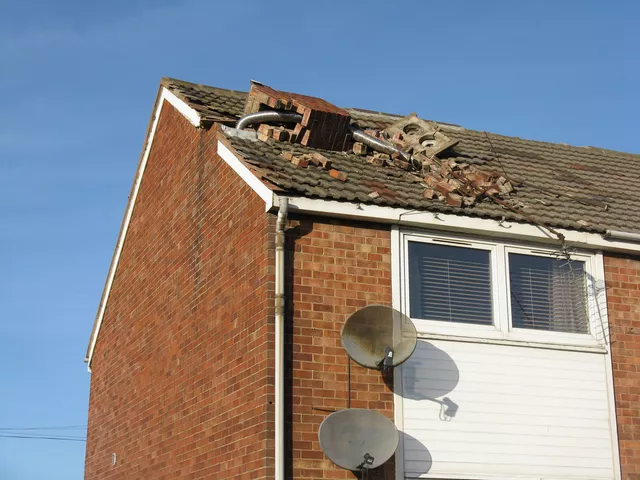
High winds and heavy rain can damage roofs, chimneys and walls, and let water into your home or business. We make sure your storm claim covers all of it, and challenge unfair decisions.
- Free assessmentNo obligation, no upfront cost
- No win, no feeWe don't get paid until you do
- Your own loss assessorFrom first call to final settlement
Storm claims are often disputed
Storm damage needs fast action to stop further harm. A few missing tiles can let in enough water to damage ceilings, insulation, electrics and belongings below.
Storm claims are also among the most frequently disputed. Insurers often look closely at whether the weather met their definition of a storm, and whether the damage was really caused by wear and tear or a lack of maintenance instead.
Our loss assessors arrange emergency works, build a complete, well-evidenced claim and represent you if the insurer pushes back, so you're not left paying for damage your policy should cover.
How we help with your storm claim
We arrange temporary repairs, such as covering a damaged roof, to stop further damage.
We gather the weather records and evidence that link the damage to the storm.
We include internal damage from rain getting in through the damaged roof or walls.
We challenge decisions that wrongly blame wear and tear or maintenance.
Somewhere to stay if your home can't be lived in, where your policy covers it.
We appoint and supervise roofers and contractors through to completion.
What a storm claim can include
Depending on your policy, these are the areas we check on every storm claim.
- Roofs and chimneysLost or broken tiles and slates, damaged flashing, ridges and chimney stacks.
- Water getting inCeilings, walls, insulation and contents damaged by rain entering through storm damage.
- Fallen treesDamage caused by trees or branches brought down by the storm.
- Outbuildings and wallsGarages, sheds and garden walls, depending on your cover.
- Fences and gatesMany policies exclude these from storm cover, so we check your wording carefully.
- Business lossesFor businesses, stock, equipment and loss of income while you recover.
Common questions
What counts as a storm for an insurance claim?
Policies often don't define it precisely, but many insurers look for strong winds, typically gusts of around 55mph or more, or exceptionally heavy rain, hail or snow. Weather records for your area and the date of the damage are key evidence, and we gather them for you.
My insurer says the damage is wear and tear. Can you help?
Yes. This is one of the most common reasons storm claims are refused. The question is usually whether there was a storm, whether the damage is consistent with storm damage, and whether the storm was the main cause. We review the evidence and challenge the decision where it isn't justified.
Should I carry out emergency repairs?
Yes. You should take reasonable steps to stop further damage, such as covering a damaged roof. Photograph the damage first and keep receipts for any emergency work, as these costs can usually be included in the claim.
Are fences and gates covered?
Many home insurance policies exclude fences, gates and hedges from storm cover. It's worth checking your policy wording, and we can do that for you.
Get your first consultation free
Talk to an experienced loss assessor about your claim. No win, no fee.
Lines open Monday to Friday, 9am to 5pm.